Forex account verification failed? See why KYC checks get rejected and the exact steps to fix it and unlock deposits/withdrawals fast.
Forex Account Verification Failed: Causes & Fixes
A forex account verification fails when submitted documents do not match broker requirements or KYC checks flag inconsistencies. Common triggers include blurry ID scans, expired documents, mismatched names, or outdated proof-of-address files. These issues are typically identified during automated or manual review before trading access is fully granted.
Accepted KYC documents generally fall into two categories: identity proof and address proof. Brokers typically accept a passport, national ID card, or driver’s license for identity verification, alongside a recent utility bill or bank statement for address confirmation. Document requirements can vary depending on the broker’s regulatory jurisdiction.
Resubmitting a rejected verification starts with correcting the specific issue flagged by the broker’s compliance team. Traders can usually upload updated documents through the account dashboard or contact support to appeal the rejection with clarification. Response times for reviewed appeals depend on the broker’s internal KYC workflow.
Verification failure directly restricts account functionality, particularly around funding. Unverified accounts commonly face blocked withdrawals and deposit limits until KYC is successfully completed. This makes resolving verification errors essential before moving funds.
Understanding these causes and fixes helps traders navigate KYC smoothly, a process Forex Bit outlines further below. The next section breaks down the specific reasons why forex account verification fails and how each cause connects to broker-side review procedures.
Why Did My Forex Account Verification Fail?
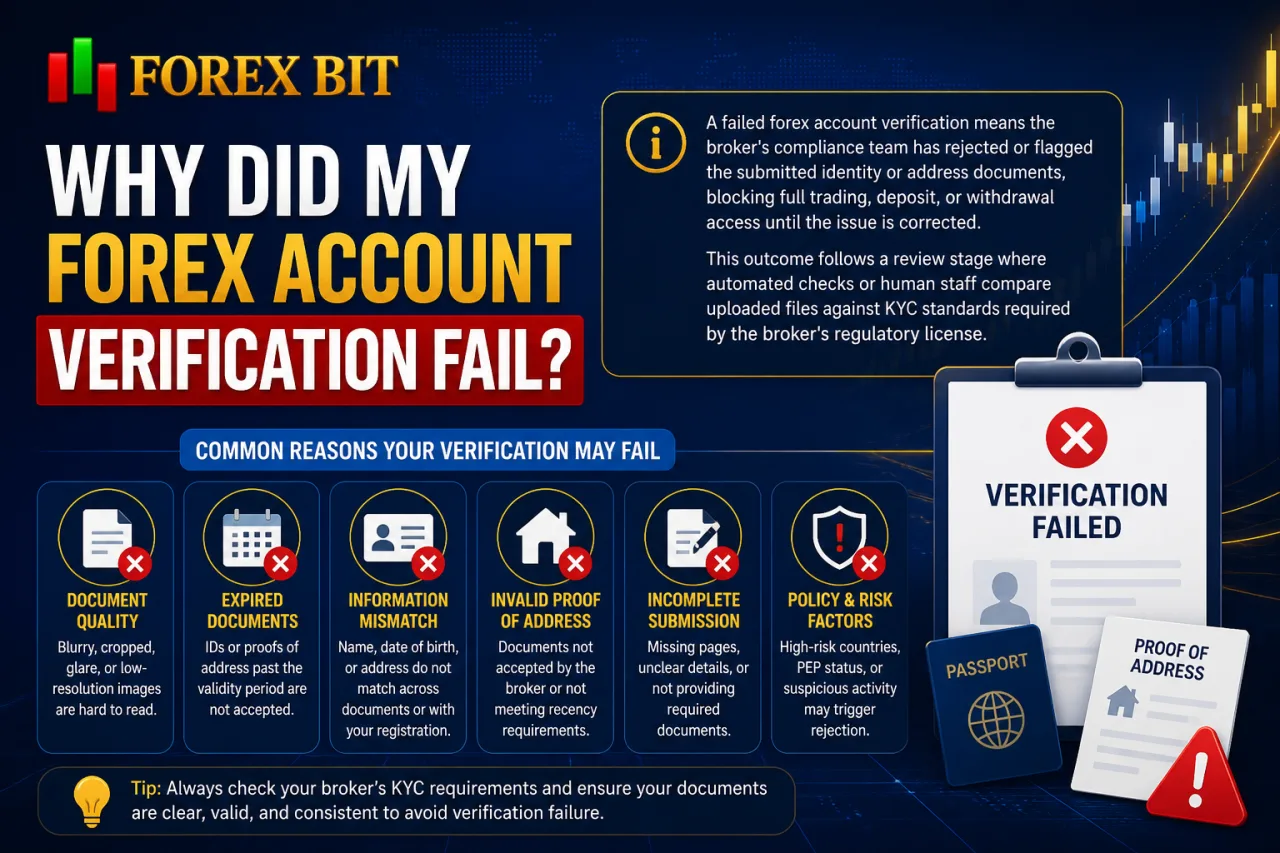
A failed forex account verification means the broker’s compliance team has rejected or flagged the submitted identity or address documents, blocking full trading, deposit, or withdrawal access until the issue is corrected. This outcome follows a review stage where automated checks or human staff compare uploaded files against KYC standards required by the broker’s regulatory license.
Verification failure connects to several recurring root causes rather than a single error. Document quality, data mismatches, and account-level inconsistencies each trigger a different type of rejection notice from the broker.
The sections below break down these root causes individually, covering how document issues, personal data mismatches, and account-related flags each lead to a failed KYC outcome.
What Are the Most Common Reasons for Verification Rejection?
Verification rejection groups into nine recurring categories: poor-quality document scans, expired IDs, name mismatches, outdated proof of address, failed selfie or liveness checks, unsupported document types, incomplete form fields, restricted-country registration, and duplicate account detection. Each category triggers a different flag inside the broker’s compliance review.
- Blurry or low-resolution photos of ID cards or passports obscure key data fields during automated scanning.
- Expired identity documents fail the validity check regardless of image quality.
- Name mismatches occur when the ID differs from the name entered during account registration.
- Address proof older than the accepted timeframe fails freshness checks. Brokers commonly require utility bills or bank statements dated within the last few months to confirm an address is current.
- Selfie or liveness verification fails when the live photo does not match the submitted ID image.
- Unsupported document types, such as expired visas or non-government IDs, get rejected outright.
- Incomplete form fields leave the compliance system unable to cross-check applicant data.
- Registration from a sanctioned or restricted country blocks verification under the broker’s regulatory license.
- Duplicate account detection flags a second registration linked to the same identity or device.
Is a Name or Address Mismatch a Common Cause of Failure?
Yes, a name or address mismatch ranks among the most frequent causes of forex verification failure, since compliance systems require exact alignment between account registration details, the ID document, and the proof-of-address file. Brokers enforce this strict matching to confirm the account holder is the same person named on official documents, satisfying anti-fraud and anti-money-laundering obligations tied to their regulatory license.
This mismatch issue often stems from small, easily overlooked details rather than deliberate errors. A middle name omitted during registration, a shortened first name, or a married versus maiden surname can each trigger a rejection flag.
Transliteration differences add another layer of risk for traders holding non-Latin-script documents. Names converted from Cyrillic, Arabic, or Chinese script into Latin characters can produce slightly different spellings across a passport, a bank statement, and the account profile, which can complicate identity matching during verification.
Address mismatches follow a similar pattern, where a utility bill listing an apartment number or abbreviated street name differs from the format entered on the account. Correcting these discrepancies before resubmission reduces the chance of a repeated rejection.
What ID and Proof-of-Address Documents Are Accepted for Forex KYC?
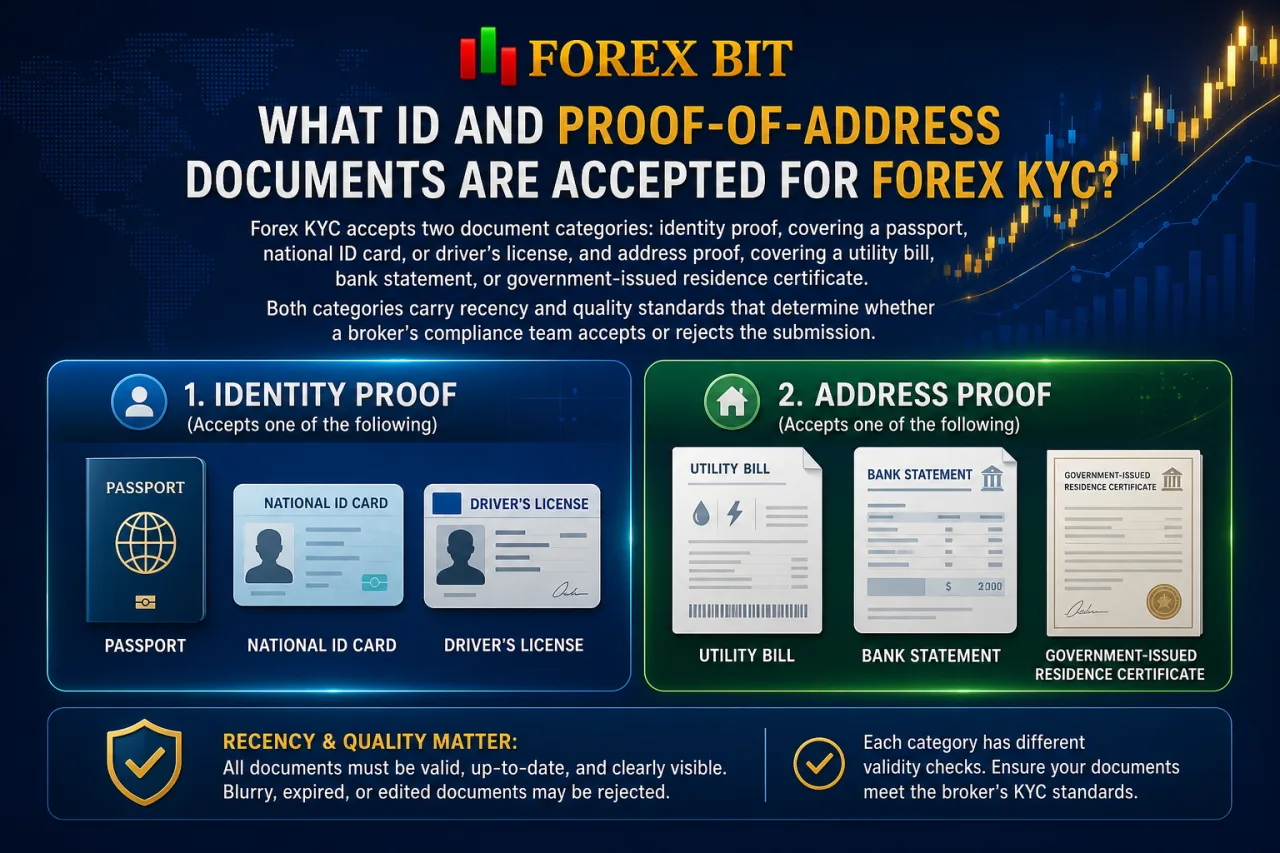
Forex KYC accepts two document categories: identity proof, covering a passport, national ID card, or driver’s license, and address proof, covering a utility bill, bank statement, or government-issued residence certificate. Both categories carry recency and quality standards that determine whether a broker’s compliance team accepts or rejects the submission.
The following breakdown separates identity document rules from address document rules, since each category applies different validity checks during review.
What Makes a Document Invalid or Unacceptable?
A document becomes invalid or unacceptable when it fails one of six checks: expiration, cropped edges, screenshot submission instead of a direct scan or photo, incorrect file format or oversized file, mismatch between the ID photo and the selfie, or a proof-of-address file listing a third-party name. Each factor triggers rejection during the broker’s compliance review, separate from the name-mismatch and freshness issues covered earlier.
These disqualifying factors typically involve either the document’s physical condition or its relationship to the applicant’s identity.
- Expired passports, national ID cards, or driver’s licenses fail the validity check regardless of clarity.
- Cropped edges hide corner details such as issue dates or security stamps needed for verification.
- Screenshots replace genuine scans with a lower-quality, potentially edited image source, prompting automatic rejection.
Oversized files or unsupported formats, such as image types the broker does not accept or files exceeding its upload size limits, get blocked before manual review even starts. - Selfie or liveness photos that do not visually match the submitted ID trigger a facial-mismatch flag.
- Proof-of-address documents listing a spouse, parent, or roommate instead of the account holder fail the ownership check, since utility bills and bank statements must display the applicant’s own name.
How Can You Fix or Resubmit a Rejected Forex Verification?
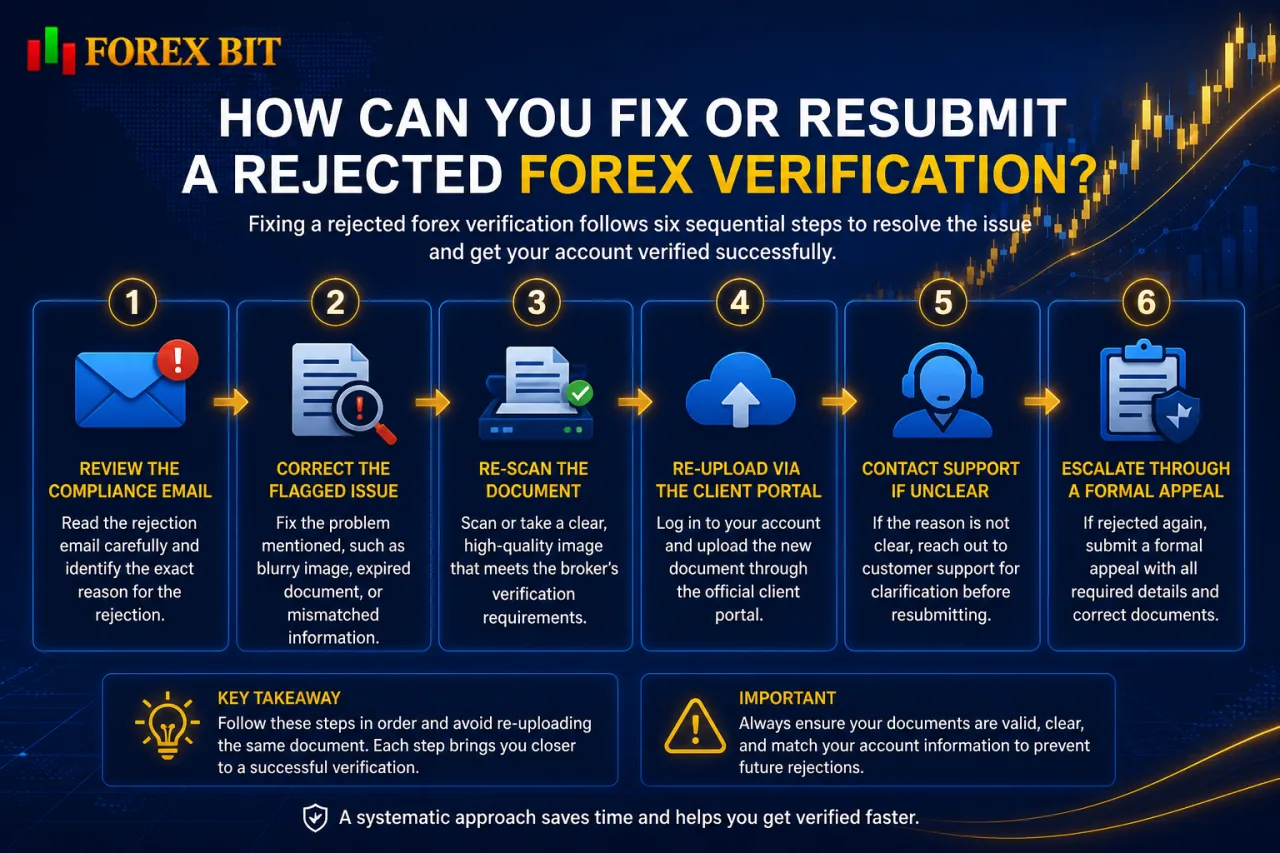
Fixing a rejected forex verification follows six sequential steps: review the compliance email, correct the flagged issue, re-scan the document, re-upload via the client portal, contact support if the reason stays unclear, and escalate through a formal appeal if resubmission fails again. This sequence addresses the rejection systematically rather than resubmitting the same file blindly.
The process starts with the broker’s rejection notice, which identifies the specific issue before any correction happens.
- Reading the rejection email or portal notification identifies the exact reason cited by the compliance team.
- Correcting the flagged issue targets the identified problem, whether a name mismatch, an expired ID, or an outdated address file.
- Re-scanning or re-photographing the document under good lighting removes glare, blur, and cropped edges from the previous submission.
- Logging into the client portal re-uploads the corrected file to the same verification queue.
- Contacting support or live chat clarifies the rejection reason when the broker’s notice lacks sufficient detail.
- Escalating through a formal appeal applies when a second resubmission gets rejected without a clear explanation, typically routing the case to a senior compliance reviewer.
Traders holding non-Latin-script documents benefit from double-checking transliteration consistency before resubmitting, since spelling variations across files trigger repeat rejections.
How Does a Failed Verification Affect Deposits and Withdrawals?
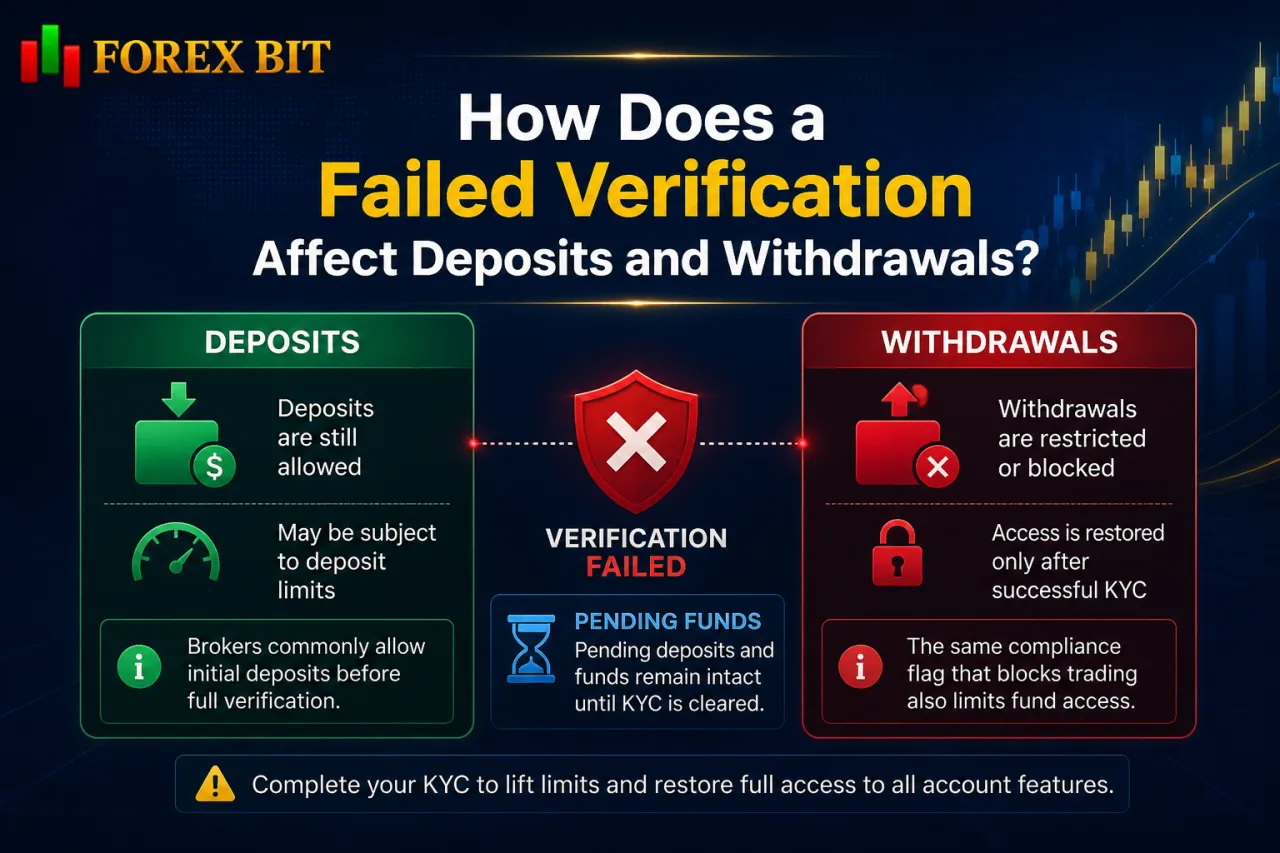
Failed verification restricts withdrawals and imposes deposit limits while leaving pending funds intact until KYC clears. This funding impact follows directly from the rejection causes covered earlier, since the same compliance flag that blocks trading access also determines what a trader can and cannot do with money already in the account.
Most brokers separate deposit access from withdrawal access during unverified status. Brokers commonly allow initial deposits before full verification, while KYC checks tend to apply more strictly at the withdrawal stage.
Several conditions define this restricted state:
- Depositing funds stays available in many cases even before documents get approved.
- Limiting deposit size applies at some brokers until verification completes, capping how much a trader can add pre-KYC.
- Blocking withdrawals remains the primary restriction, preventing fund transfers out of the account until compliance approves the submitted documents.
- Holding pending funds keeps the balance visible and accessible within the account, since restricted status limits access rather than removing the money itself.
Resolving the flagged document issue, following the resubmission steps described earlier, restores full withdrawal capability once compliance approves the updated file.
Are There Additional Checks Beyond Standard ID Verification?
Yes, brokers apply additional checks beyond standard ID verification, covering source-of-funds requests, enhanced due diligence for politically exposed persons, and periodic re-verification. These layers move past the document-rejection scenarios covered earlier, targeting risk factors tied to transaction size, applicant status, or account dormancy rather than file quality alone.
Each check activates under a different trigger inside the broker’s compliance framework, ranging from large fund movements to profile changes flagged after account inactivity.
Do Regulatory Jurisdictions Change Verification Requirements?
Yes, regulatory jurisdiction changes forex verification requirements, since brokers licensed under top-tier regulators such as the FCA, ASIC, or CySEC apply stricter document and source-of-funds checks than offshore-licensed entities. This tier-based gap connects directly to the additional checks noted above, since the regulatory framework a broker operates under determines how deep those checks go.
Top-tier regulated brokers typically enforce mandatory identity and address verification before any withdrawal, alongside stricter document freshness rules and closer scrutiny of name-matching accuracy. Offshore entities often apply lighter document checks and faster approval, though this tends to come with reduced investor protection compared to top-tier licensing.
Traders registering from certain countries also face jurisdiction-specific outcomes:
- Facing higher rejection rates applies to applicants submitting documents that meet offshore standards but fall short of top-tier regulator requirements.
- Triggering enhanced due diligence applies more frequently under top-tier licenses, particularly for larger deposits or withdrawal requests.
- Encountering restricted registration applies to residents of countries excluded from a broker’s regulatory license territory.
Conclusion
Forex verification failures trace back to a narrow set of fixable problems: poor document quality, expired IDs, name or address mismatches, and account-level flags like duplicate registration or restricted-country access. Correcting the specific flagged issue, re-scanning documents properly, and resubmitting through the client portal resolves most rejections, while unclear cases warrant direct support contact or formal appeal.
Since blocked withdrawals and deposit limits stem directly from unresolved KYC status, clearing the flagged document restores full account functionality. Regulatory jurisdiction shapes how strict this process becomes, with top-tier licensed brokers applying tighter document and source-of-funds standards than offshore entities, making jurisdiction awareness part of avoiding repeated rejection.
William Johnson is a Forex & Broker News Analyst at Forex Bit, focusing on broker updates, regulatory developments, payment changes, and security-related news. His work helps readers stay informed about important industry developments and understand how these changes may affect broker services and trading conditions.
Email: [email protected]
Best Brokers

Trade with the world’s largest retail broker and benefit from better - than - market conditions.

We offer a superior trading environment that puts traders in the best position to profit.

Trade with the best trading conditions. WIN THE BEST TRADING ACCOUNT AWARD.

Trade global markets with Interactive Brokers – a highly regulated multi-asset broker built for active and professional investors.
Forex Bit provides in-depth analysis of commodities, forex, and stock markets to help traders make informed investment decisions.
Best Brokers
Metatrader 5 Brokers
Metatrader 4 Brokers
Lowest Spread Forex Broker
Regulated Forex Brokers
Forex Copy Trading
Ctrader Brokers
Best Forex Broker For Beginners